
Jacksonville Business Valuation Guide: What Buyers Will Pay
See Your Jacksonville Business Through a Buyer’s Valuation Lens
Jacksonville buyers weigh normalized earnings alongside customer concentration, owner dependence, recurring revenue, operational depth, and financing. To assess what qualified buyers may pay for your company, schedule a confidential exit-planning conversation.
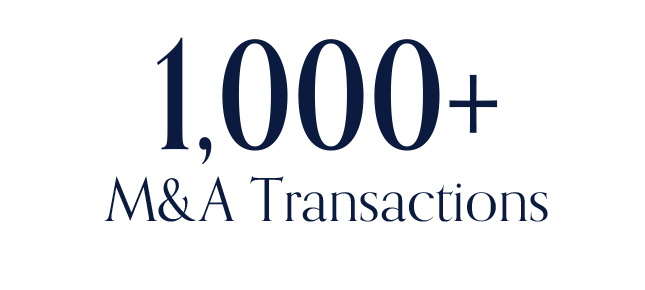


Why Jacksonville Business Owners Choose Sailfish Equity Advisors
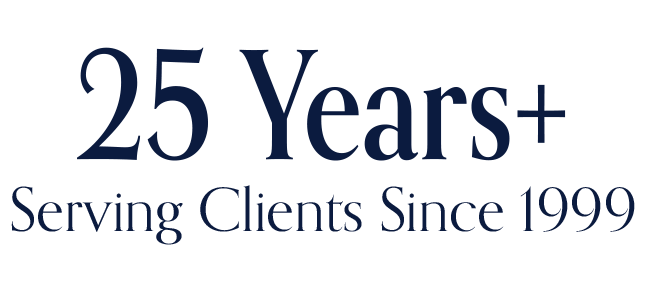
25+ Years of Proven Deal Experience
1,000+ Businesses Sold Across Florida
Confidential, Strategic Sale Process
Access to a Qualified Buyer Network
Maximized Valuation Through Positioning
Industry Experience Across High-Demand Sectors
Deal Structuring Expertise
Hands-On Guidance From Start to Finish
Deep Local Market Knowledge in Jacksonville, FL
Built for Results—Not Just Listings
1,000+ Florida Business Owners Trust Us
Real stories from owners who sold, scaled, and succeeded with Sailfish.
Now is the Perfect Time to Sell Your Business in Jacksonville, FL:
Many owner-operated Jacksonville businesses may trade around 1.5 to 3.5 times Seller’s Discretionary Earnings, but that range is only a starting point. A credible Jacksonville business valuation must test the earnings, financing, customer concentration, management depth, transferability, industry demand, and risks a qualified buyer will inherit.
Sailfish Equity Advisors is a Florida sell-side M&A and business-brokerage practice serving Jacksonville and Northeast Florida owners. We value companies through the lens of buyers and lenders, identify issues that can weaken an offer, prepare the supporting records, and manage confidential sale processes when an owner decides to move forward.
Build a Defensible Value Range From Earnings, Risk, and Transferability
Owners naturally remember the capital invested, difficult years survived, relationships built, and sacrifices made. A buyer starts elsewhere: how much cash flow can be verified, how likely it is to continue, what must be invested after closing, and whether the company can operate when the seller leaves.
That is why valuation is better understood as a range than as one perfect number. The lower end reflects weak evidence or greater risk. The upper end requires cleaner earnings, stronger transferability, credible growth, and enough buyer or lender support to close at that level.
A useful valuation should answer five questions. What does the company truly earn? Which measure fits its size and buyer pool? What multiple does the risk support? Can the likely buyer finance the price? What changes could improve the range before the business goes to market?
Step 1: Reconstruct the Earnings a Buyer Can Verify
For many owner-operated small businesses, the starting measure is Seller’s Discretionary Earnings, or SDE. It estimates the economic benefit available to one full-time owner-operator.
The calculation often begins with net income and may add back one owner’s compensation, owner benefits, interest, depreciation, and legitimate one-time or discretionary expenses. The purpose is not to inflate the result. It is to separate the company’s continuing operating expenses from costs that would not remain under a new owner.
Each adjustment needs support. A one-time legal bill, documented personal vehicle expense, or excess owner compensation may be defensible. A recurring expense with no invoice or explanation may not be. Buyers and lenders frequently compare the add-back schedule with tax returns, profit-and-loss statements, payroll records, and bank activity.
When the evidence supports $350,000 of SDE but the seller’s estimate depends on another $100,000 of uncertain adjustments, the market will generally value the supported figure. Clean earnings create negotiating credibility; aggressive adjustments create doubt that can spread to the rest of the records.
Step 2: Use the Valuation Method That Fits the Company
SDE is common for companies expected to be purchased and operated by an individual owner. Larger businesses with management in place may be evaluated using EBITDA, which measures earnings before interest, taxes, depreciation, and amortization. Asset-heavy or distressed companies may also require an asset approach, while recurring-contract businesses may be compared with similar completed transactions.
No single formula fits every Jacksonville company. A logistics-support business with equipment and contracts, a professional practice tied to one rainmaker, and a commercial maintenance company with hundreds of recurring accounts can produce the same annual earnings and still deserve different risk assessments.
The valuation method should match the likely buyer. An individual using acquisition financing focuses on owner benefit and debt coverage. A strategic acquirer may see customer, workforce, license, territory, or cross-selling value that an individual cannot capture. A private-equity-backed buyer may focus on EBITDA, management depth, recurring revenue, and whether the company can operate as an add-on.
Step 3: Apply a Multiple That Reflects Risk
A multiple is a compressed judgment about future confidence. Higher does not mean the seller worked harder. It means the buyer perceives more durable earnings and fewer ways for the investment to fail.
Factors that can support the upper end of a range include recurring or repeat revenue, diversified customers, stable margins, documented systems, an experienced team, transferable contracts, modest capital needs, and growth opportunities supported by actual capacity or demand.
Factors that can pull the range downward include declining earnings, inconsistent books, one customer representing more than roughly 20% to 30% of revenue, unresolved legal or tax issues, an expiring lease, aging equipment, high employee turnover, or a business that depends on the seller for every important relationship and decision.
The quality of earnings can matter more than the amount. Two companies may each report $500,000 of SDE. If one has recurring contracts, a supervisor who runs daily operations, and no customer above 10% of sales, buyers may view it very differently from a company whose largest customer supplies 35% of revenue and whose owner handles sales, pricing, and service recovery.
How Jacksonville Industry Conditions Change the Risk Review
Jacksonville’s mix of logistics, distribution, industrial services, construction, skilled trades, healthcare, marine activity, manufacturing, and professional services creates several distinct buyer lenses. The location may create interest, but company-specific evidence determines whether that interest becomes a strong offer.
Logistics, Distribution, and Warehousing
Buyers may examine route density, customer and vendor contracts, dispatch systems, equipment condition, driver or operator retention, and dependence on one shipper or account. Proximity to transportation infrastructure can support the story, but it does not offset a concentrated customer base or a fleet requiring immediate replacement.
Marine, Aviation, Manufacturing, and Industrial Services
Certifications, technical employees, production systems, safety history, equipment, backlog, and customer relationships can materially influence value. The key question is whether specialized knowledge belongs to the company or exists only with the owner.
Construction and Skilled Trades
Licensing, qualified employees, project mix, gross margins, safety record, backlog quality, service agreements, and referral concentration matter. A full pipeline is valuable only when the jobs are profitable, contracts are transferable, and the team can deliver the work after a sale.
Professional and Healthcare Services
Buyers look closely at provider or professional dependence, referral sources, client retention, compliance, billing quality, and whether other team members own meaningful relationships. A practice can be profitable yet difficult to transfer if every client expects one individual to remain indefinitely.
Recurring-Revenue Service Companies
Commercial maintenance, HVAC service, pest control, landscaping, janitorial, pool service, and similar companies can benefit from predictable revenue. Buyers still test cancellation terms, account retention, route efficiency, labor stability, and the margin produced by those contracts. Recurring revenue earns a premium only when it is durable and profitable.
Financing Can Set the Practical Ceiling
A valuation is not complete until the likely transaction can be financed. A lender evaluates documented historical cash flow, debt-service coverage, buyer qualifications, collateral where applicable, and whether the company can support the purchase without starving normal operations.
If a price requires earnings that cannot be verified, lenders may reduce the supported loan amount. The buyer must then contribute more cash, ask the seller to finance part of the purchase, renegotiate the price, or leave the transaction.
This is the difference between a spreadsheet value and a marketable value. The first can be generated by assumptions. The second must survive buyer review, lender underwriting, and due diligence. Testing financing early helps prevent an owner from spending months defending a price that the most likely buyers cannot close.
Transferability Is Often the Largest Adjustment
Owner dependence can affect value even when revenue is strong. Buyers become cautious when the seller controls all sales, holds the largest customer relationships, approves every price, knows every password, resolves every employee problem, and carries the operating process in memory. - Jacksonville Business Brokers
Reducing that risk does not require the owner to disappear. It requires responsibilities and knowledge to become transferable. Document estimating, scheduling, quality control, purchasing, collections, hiring, training, and customer-service procedures. Cross-train employees. Share major relationships with managers. Give the team authority appropriate to their roles.
A buyer who can see how the company operates after closing has more confidence in the cash flow. That confidence can improve buyer interest, deal structure, financing support, and the valuation range.
The Evidence Behind a Credible Jacksonville Valuation
Prepare the records a buyer will eventually request: three years of tax returns and financial statements, current-year results, balance sheets, bank and payroll support, an add-back schedule, customer concentration reports, leases, licenses, contracts, insurance, equipment lists, employee summaries, organizational charts, and documented procedures.
Review the file for inconsistencies before a buyer does. Explain revenue changes, margin swings, unusual expenses, related-party payments, one-time events, and any difference between the tax returns and internal statements. Confirm whether leases, contracts, licenses, and permits can continue after ownership changes.
Good documentation does more than speed up due diligence. It makes the valuation more believable. A buyer is less likely to discount a risk that has been identified, measured, and addressed than one discovered unexpectedly after an offer.
A Practical Plan to Improve Value Before Selling
Begin with the factors a buyer would discount today. Organize the financial records and document every add-back. Address a large customer concentration where possible. Renew important contracts or leases. Repair compliance gaps. Clarify employee responsibilities. Build a second layer of decision-making. Document the processes that currently depend on the owner.
Then strengthen the earnings story. Improve pricing discipline, remove unprofitable work, track margins by service or customer, protect recurring accounts, reduce preventable employee turnover, and turn believable growth opportunities into specific operating plans.
Not every improvement raises the multiple. Some protect the existing range by removing reasons for a buyer to reduce the price. That is still valuable. The best time to perform this work is before the owner must sell, while there is time to show the improvement in actual results.
How Sailfish Values a Jacksonville Business
Sailfish begins with the financial record, reconstructs supportable cash flow, and reviews the company through likely buyer and lender perspectives. The analysis considers industry conditions, customer concentration, recurring revenue, employees, management, owner involvement, contracts, assets, financing, growth, and transaction risks.
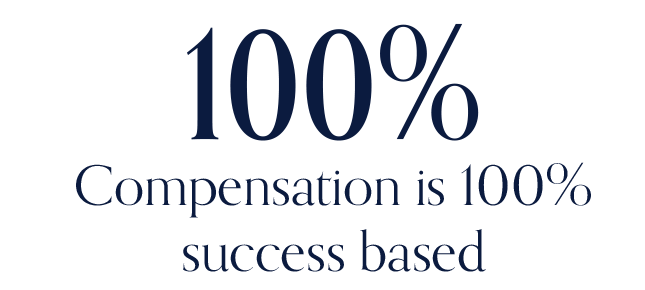
The team brings more than 25 years of Florida transaction experience and has helped over 1,000 business owners. If the owner decides to sell, Sailfish can carry the work into preparation, confidential marketing, buyer qualification, offer comparison, due diligence, and closing. There is no upfront fee; Sailfish is paid when a transaction closes.
Jacksonville Business Valuation FAQ
How much is my Jacksonville business worth?
Many owner-operated companies may trade around 1.5 to 3.5 times SDE, but the actual range depends on earnings quality, industry, recurring revenue, customer concentration, transferability, management depth, assets, growth, financing, and buyer demand. A company-specific review is more reliable than applying one general multiple.
What is Seller’s Discretionary Earnings?
SDE estimates the cash flow available to one full-time owner-operator. It commonly begins with net income and may add back one owner’s compensation, owner benefits, interest, depreciation, and legitimate one-time or discretionary expenses. Every adjustment should be documented and acceptable to buyers and lenders.
Does revenue determine business value?
Revenue is useful context, but buyers generally focus more heavily on the earnings produced by that revenue and the risk of continuing them. High revenue with weak margins, concentrated customers, or heavy capital needs can be less valuable than lower revenue producing stable, transferable cash flow.
Why does owner dependence reduce value?
If customer relationships, sales, pricing, operations, and employee decisions depend on the seller, the buyer inherits transition risk. Documented systems, shared relationships, trained managers, and clear roles make the earnings more transferable and can improve buyer confidence.
What documents are needed for a business valuation?
Start with three years of tax returns and financial statements, current-year results, balance sheets, payroll and bank support, and an add-back schedule. Depending on the company, the review may also need leases, contracts, customer reports, licenses, equipment lists, employee information, and operating procedures.
How can I improve my valuation before selling?
Strengthen the records, document add-backs, reduce owner dependence, address customer concentration, improve recurring revenue and margins, retain key employees, renew important agreements, and resolve legal, tax, lease, or licensing issues before buyers discover them.
Get a Buyer-Grounded Jacksonville Value Range
An owner does not need to be ready to sell immediately to benefit from knowing the company’s defensible value and current risk adjustments. Start with Sailfish Equity Advisors’ Jacksonville business valuation and sale guidance to understand the likely range, the evidence supporting it, and the improvements that could strengthen it.
For statewide guidance on valuation, confidentiality, buyer qualification, and closing, visit our Florida business broker guide.